On a Saturday afternoon in 1986, a teenager in suburban Ohio laced up her sneakers and asked her mother for a ride. There was no errand, no shopping list, nothing specific to buy. She simply wanted to go to the mall. That was the entire plan, and it was enough.
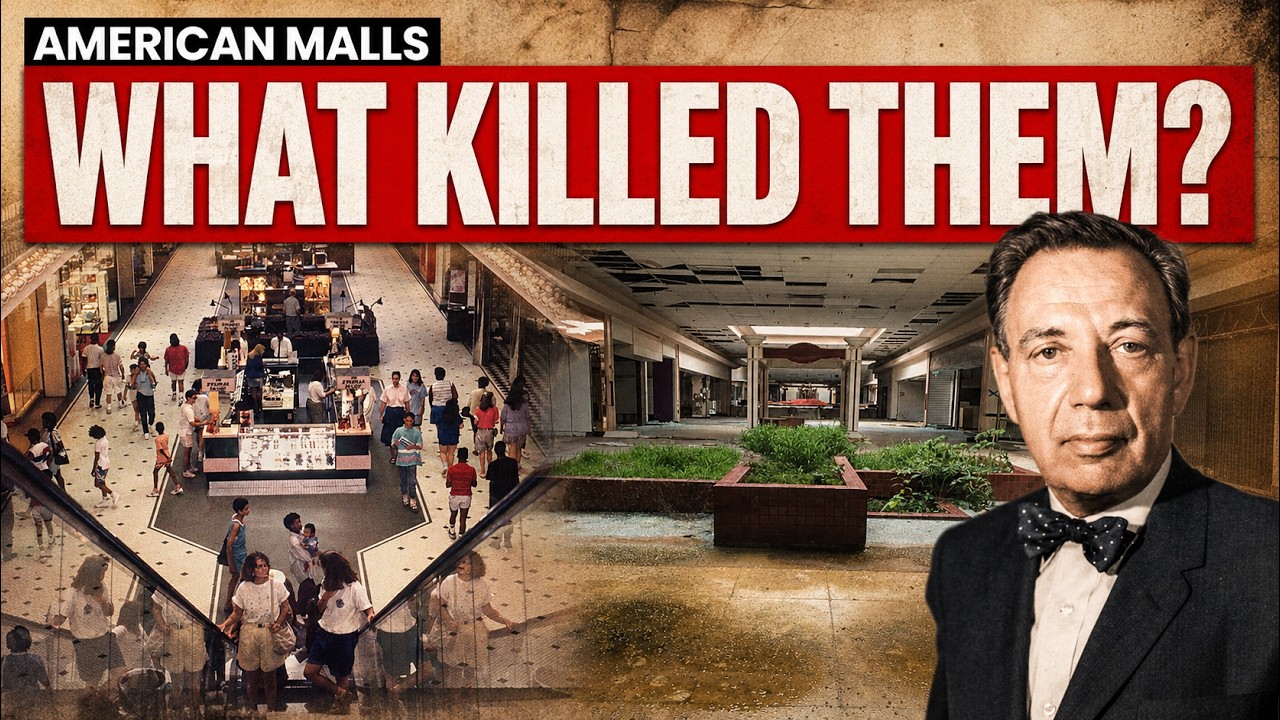
She would wander past neon signs, flip through cassette tapes, eat cheap pizza under fluorescent lights, try on clothes she could not afford, and run into half her school. The mall was not merely a place to shop. It was the town square, the playground, the living room, and the social center of an entire generation. Today, that same spot looks like something from a post-apocalyptic film.
Water-stained ceilings, shattered skylights, escalators frozen mid-step, dry fountains, a dark food court, and a parking lot cracked and overgrown with weeds. At their peak in the late 1980s, America had roughly 2,500 enclosed shopping malls. Today, fewer than 700 remain, and by some estimates, that number could fall to as few as 150 by the early 2030s. No new mega mall has been built in the United States since 2006.
Over the last decade, an average of 40 malls closed every year, and in 2025 alone, nearly 6,000 mall-based stores shut their doors, a 67 percent increase from the year before. The story of how this happened begins not with the internet, but with a socialist architect from Vienna named Victor Gruen. Born Victor David Grünbaum in 1903, Gruen was Jewish, an avant-garde architect, and a performer of satirical cabaret. When the Nazis annexed Austria in 1938, he fled to America with almost nothing.
He landed in New York, changed his name, and began designing storefronts on Fifth Avenue. But Gruen had a much larger vision. Looking at the new American suburbs built after the Second World War, he saw communities without centers, families isolated in identical ranch houses with no public gathering place. The GI Bill had given returning soldiers cheap mortgages and affordable education, and millions of families fled the cities for three-bedroom homes with two-car garages.
But moving thirty miles outside the city meant moving thirty miles away from restaurants, shops, theaters, and doctors. The suburbs had houses, but they did not have life. Gruen dreamed of something revolutionary: an enclosed, climate-controlled community hub that combined stores with gardens, art, medical facilities, schools, and public squares. He wanted to replicate the vibrant street life of Vienna in the middle of the American suburbs.
In 1952, the Dayton family, prominent department store merchants from Minneapolis, commissioned him to bring that vision to life. On October 8, 1956, the Southdale Center opened in Edina, Minnesota. It was the first fully enclosed, climate-controlled shopping mall in the United States, an 800,000-square-foot complex with 72 stores, 5,000 parking spots, and two anchor department stores placed at opposite ends to pull foot traffic past every smaller shop in between. The temperature inside was kept at a constant 75 degrees, a miracle for a region with brutal winters.
Gruen also engineered something subtler into the design, a psychological phenomenon later known as the Gruen transfer. The corridors curved, the sightlines shifted, and the lighting and music were all crafted to create a pleasant confusion that made shoppers forget what they came for and begin buying things they had not planned on. It was consumer psychology weaponized through architecture, and it worked. Life magazine called Southdale the splashiest shopping center in the country, and developers across America rushed to replicate the model.
By the mid-1970s, more than a thousand enclosed malls had been built. They followed an identical formula: two or three massive department stores as anchor tenants at opposite ends, a corridor of specialty shops between them, a food court near the center, a movie theater, an arcade, a fountain, and acres of free parking. The malls did not just change how Americans shopped. In suburbs with no downtown and no main street, the mall became the place for first dates, first jobs, ear piercings, and after-school hangouts.
For a long time, the arrangement worked beautifully for developers, retailers, and the millions of families who organized their weekends around it. But the model was not built to last. Through the 1970s and 1980s, the mall did not just grow; it metastasized. Developers realized malls were profit machines.
The formula was simple: buy cheap land on the suburban fringe, build the mall, watch the surrounding area explode with new housing and commercial development, and watch property values skyrocket. Anchor tenants signed long leases, smaller retailers paid premium rents for the foot traffic, and tax revenue poured into local governments. Everyone got rich, so they kept building. By 1986, America had roughly 25,000 retail malls and shopping centers.
Americans spent an average of twelve hours per month inside them. The country had accumulated nearly 24 square feet of retail space per person, ten to twenty times more than any other developed nation. Nobody stopped to ask whether that made sense. Each new mall required cheap land, so developers built further and further out.
New housing surrounded the new mall, families drifted away from older neighborhoods, and when an even larger, flashier mall was built even further out, the cycle repeated. The original mall lost its customer base, property values fell, retailers left, and the old mall deteriorated. This was the suburban sprawl death spiral, baked into the model from the very beginning. Every new mall was a ticking clock for the one that came before it.
Through the 1980s and 1990s, none of this mattered because the money was still flowing. The mall was the backdrop of American culture. Fast Times at Ridgemont High in 1982 was a love letter to mall culture. Tiffany performed her hit single on a mall tour in 1987.
The Mall of America opened in Bloomington, Minnesota, in 1992, a 5. 6-million-square-foot behemoth with an indoor amusement park, an aquarium, and over 500 stores. But beneath the surface, the foundation was already cracking. The entire economic model of the American mall rested on one pillar: the anchor tenant.
These massive department stores, names like Sears, JCPenney, Macy’s, and Nordstrom, drew the foot traffic, paid for the advertising, and kept the smaller specialty shops alive. In return, they paid far lower rents than smaller tenants, often almost nothing, because their value was in the crowds. This arrangement worked as long as the anchors stayed healthy. Starting in the late 1990s and accelerating through the 2000s, the American department store began to die.
Sears, once one of the ten most valuable companies in America and an era-defining retailer that operated roughly 3,500 stores at its height, filed for bankruptcy in October 2018. By 2025, fewer than ten Sears stores remained. JCPenney followed a similar path, closing around 200 stores during its 2020 bankruptcy. Macy’s announced plans in February 2024 to shutter 150 stores by 2026.
Lord and Taylor closed entirely, and Bon-Ton, a chain with 250 locations, liquidated in 2018. The impact on malls was catastrophic. When an anchor tenant closes, foot traffic to that mall drops by 20 to 25 percent almost immediately. But the damage goes further.
Most smaller tenants have co-tenancy clauses in their leases, meaning that if a major anchor leaves, they can renegotiate their rent downward or break their lease entirely. When Sears closed, the shoe store next to it started paying less rent, the clothing boutique triggered its exit clause, and the pretzel stand lost half its customers. The entire ecosystem collapsed inward like a building losing its load-bearing walls. The other major external force was the rise of e-commerce.
In 1994, Jeff Bezos founded a small online bookstore in his garage in Bellevue, Washington, called Amazon. Within a decade, it had expanded into almost everything. By 2017, a Business Insider analysis concluded that Amazon alone was generating more than 50 percent of all retail sales growth in the United States. E-commerce did not just compete with physical stores; it undermined the very reason people went to malls.
The mall’s value proposition had been convenience, everything under one roof. But when you could find everything on a screen and have it delivered to your door the next day, that argument evaporated overnight. Then came March 2020 and the COVID-19 pandemic. Malls closed for weeks and sometimes months.
A record 12,000 stores closed in 2020 alone. JCPenney, J. Crew, Neiman Marcus, and Brooks Brothers all filed for bankruptcy. The pandemic permanently changed habits.
Shoppers who discovered they could get everything delivered, many never came back. Even by 2024, mall foot traffic remained 35 percent below pre-pandemic levels. But e-commerce and the pandemic were accelerants, not the root cause. The root cause was structural and had been building for decades.
America was grotesquely overbuilt in retail. The 24 square feet of retail space per person was eight times more than Spain, nine times more than Italy, eleven times more than Germany, and roughly 400 times more than India. Nobody on Earth needed that much retail, but developers kept building because the economics were irresistible in the short term, and the consequences were someone else’s problem in the long term. Commercial real estate was incentivized by the tax code, cheap debt, and the ability to flip properties.
Local governments offered tax breaks and infrastructure subsidies to lure developers, hoping for sales tax revenue and jobs. But when three malls were built within twenty miles of each other, all competing for the same shoppers, the math stopped working. The pie did not get bigger; it just got sliced thinner. Not all malls are dying equally.
The industry is splitting in two. Premium class A malls in wealthy, high-traffic locations, like South Coast Plaza in California, the Galleria in Houston, and Tysons Corner Center in Virginia, have occupancy rates around 95 percent and have seen a 12 percent increase in foot traffic since the pandemic. They have reinvented themselves as luxury destinations where people go to dine, see art, and attend events. On the other end are class B, C, and D malls in smaller cities and declining suburbs.
An estimated 31 percent of all American malls fall into this lower tier, many of them zombie malls, technically still open but functionally dead, with vacancy rates 248 percent higher than the overall retail average. The average vacant mall sells at 43 percent below its original acquisition price, and once a mall goes dark, it stays dark for an average of nearly four years. What happens to dead malls turns out to be one of the more fascinating parts of the story. A dead shopping mall sitting on fifty acres of prime suburban land near a highway interchange is a redevelopment goldmine.
Nearly half of all mall redevelopments are mixed-use projects combining retail, residential, and commercial space. Thirty-one percent of vacant malls are reborn with new retail tenants. Nine percent become warehouses. Seven percent become residential housing.
Five percent become delivery and distribution centers, many of them serving the very e-commerce companies that helped kill the mall. Four percent become community colleges, medical facilities, or civic spaces. Landmark Mall in Alexandria, Virginia, closed in 2017, and the 51-acre site is now being redeveloped into a $2 billion mixed-use community with 4,400 apartments, a hospital, parks, and retail space. Amazon itself has partnered with Simon Property Group to convert former Sears and JCPenney spaces into fulfillment centers.
The company that did more than any other to destroy the American mall is now literally moving into the buildings it killed. Victor Gruen lived long enough to see what his creation became, and he hated it. By the 1970s, he had publicly disowned the suburban shopping mall, calling it a bastardization of his original vision. He had dreamed of a community center that happened to include shops.
America built a consumption machine that happened to have air conditioning. Gruen moved back to Vienna in 1968 and spent the last decade of his life advocating for walkable, mixed-use urban neighborhoods. He died in 1980, just as the mall was entering its most excessive and culturally dominant phase. He never saw the collapse, but the collapse was inevitable.
The American mall was built on assumptions that all turned out to be wrong: that suburbs would keep growing forever, that department stores would always anchor the model, that Americans would always prefer driving to a climate-controlled box over every other form of shopping and socializing, and that you could keep building retail space indefinitely without saturating the market. Every one of those assumptions shattered. The dead malls are not just a retail story. They are a mirror reflecting an entire way of thinking about growth, community, and public space.
The luxury malls will survive, and the ones that reinvent themselves as mixed-use hubs will survive too. The mall of the future, if it exists at all, will not be a shopping center. It will be a community center that happens to have some stores, which is exactly what Victor Gruen wanted in the first place.






