The escalator at the old mall still stands, frozen mid-step, a staircase to nowhere. Water-stained ceilings sag overhead, shattered skylights let in the rain, and entire corridors sit swallowed by silence. The fountains are dry. The food court is dark.
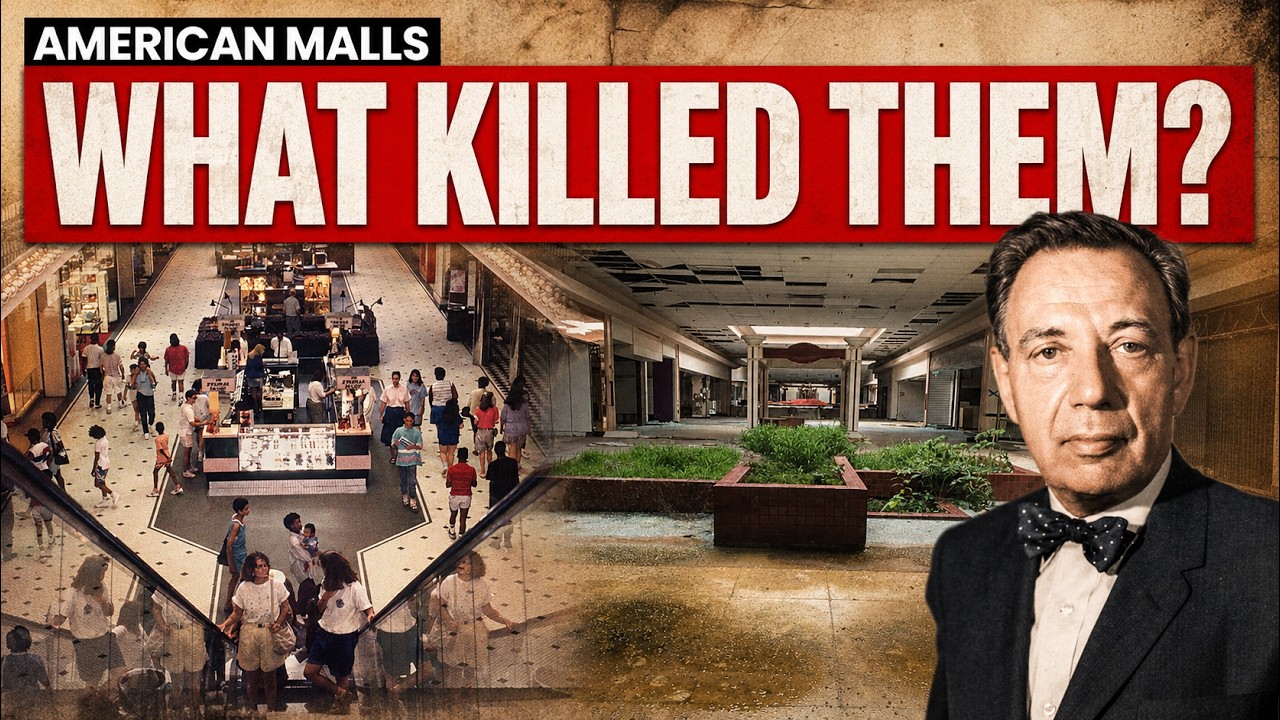
The parking lot, once overflowing on weekends, is now cracked concrete stretching in every direction with weeds pushing through the seams. In 1986, a teenager in suburban Ohio only had to lace up her sneakers and beg her mom for a ride. There was no shopping list, no errand. She just wanted to go to the mall.
That was the entire plan for a Saturday afternoon, and it was enough. She would wander through a maze of neon signs, flip through cassette tapes at the record store, eat cheap pizza in a fluorescent-lit food court, maybe try on clothes she could not afford, and bump into half her school in the process. The mall was not just a place to buy things. It was the center of American social life, the town square, the playground, the gathering place for an entire generation.
At their absolute peak in the late 1980s, America had roughly 2,500 enclosed shopping malls dotting the suburban landscape. Today, fewer than 700 remain, and by some estimates, that number could fall to as few as 150 by the early 2030s. No new mega mall has been built in the United States since 2006. Over the last decade, an average of 40 shopping malls closed every single year, and in 2025 alone, nearly 6,000 mall-based stores shut their doors, a 67% increase from the year before.
The answer to how this happened is not as simple as the internet killed it. It is a story about architecture, ambition, greed, psychology, government policy, cultural transformation, and the slow unraveling of a model that was never built to last. To understand how the American mall died, you first have to understand how it was born. The year is 1956.
Eisenhower is president, the Cold War is heating up, and across America something massive is happening beneath the surface of everyday life. Millions of families are fleeing the cities. The GI Bill, passed after the Second World War, gave returning soldiers access to cheap mortgages and affordable education. Suddenly the American dream was not a metaphor.
It was a three-bedroom ranch house with a two-car garage, a manicured lawn, and a street full of identical homes stretching to the horizon. But there was a problem with this new suburban paradise. When you moved your family 30 miles outside the city, you also moved them 30 miles away from everything else. Restaurants, shops, theaters, doctors, barbers, bookstores.
All of it was back in the old downtown, and commuting back just to pick up groceries or a pair of shoes was exhausting. The suburbs had houses, but they did not have life. Enter a man named Victor Gruen, and this is where the story gets genuinely strange, because the father of the American shopping mall was about as far from a suburban capitalist as you could possibly imagine. Gruen was born Victor David Grünbaum in Vienna, Austria, in 1903.
He was Jewish, a socialist, and an avant-garde architect who performed satirical cabaret at night. When the Nazis annexed Austria in 1938, Gruen fled to America with practically nothing. He landed in New York, changed his name, and started designing storefronts on Fifth Avenue. But Gruen had a much bigger vision.
He looked at these new American suburbs and saw communities without centers, neighborhoods without gathering places, families isolated in their homes with no public space to meet, talk, or just exist together. So he dreamed up something revolutionary. Not a shopping center, not exactly. What Gruen envisioned was an enclosed, climate-controlled community hub, a place that combined stores with gardens, art, medical facilities, schools, and public squares.
A place that would replicate the vibrant street life of his beloved Vienna, right in the middle of the American suburbs. In 1952, the Dayton family, prominent department store merchants from Minneapolis, commissioned Gruen to bring his vision to life. And on October 8, 1956, the Southdale Center opened its doors in Edina, Minnesota, a suburb of Minneapolis. It was the first fully enclosed, climate-controlled shopping mall in the United States, and it was unlike anything Americans had ever seen.
Southdale was enormous, 800,000 square feet of retail space, 72 stores, 5,000 parking spots, two anchor department stores placed at opposite ends, designed to pull foot traffic past every smaller shop in between. There was a central garden court flooded with natural light, filled with trees, sculptures, birdcages, and a sense of openness that felt almost European. The temperature inside was kept at a constant 75 degrees, a miracle for a region where winters were brutal. Gruen had also designed something into the layout that was subtler and far more powerful than climate control.
It was a psychological phenomenon that would later become known as the Gruen transfer, sometimes called the Gruen effect. The layout of Southdale was deliberately disorienting. The corridors curved, the sightlines shifted, the lighting, the music, the spatial design, all of it was engineered to create a kind of pleasant confusion, a dreamlike state in which shoppers forgot what they came in for and began wandering, browsing, and making purchases they had not planned on. It was consumer psychology weaponized through architecture, and it worked devastatingly well.
Life magazine ran a feature on Southdale in December of 1956, calling it the splashiest shopping center in the country. Developers from coast to coast took notice, and almost overnight, the race to replicate Gruen’s model began. Over the next two decades, the American mall multiplied like nothing before it. By the mid-1970s, more than a thousand enclosed malls had been built across the United States.
They followed a nearly identical formula: two to three massive department stores, what the industry called anchor tenants, positioned at opposite ends of the complex, with a long corridor of specialty shops between them, a food court somewhere near the center, maybe a movie theater, an arcade, a fountain or two, and acres of free parking. The malls did not just change how Americans shopped, they changed how Americans lived. In suburbs that had no downtown, no main street, no public park worth mentioning, the mall became all of those things. It was where you got your ears pierced, where you had your first date, where you applied for your first job, where you went on Christmas Eve, where you hung out after school because there was literally nowhere else to go.
The mall was America’s living room, and for a long time that arrangement worked beautifully for the developers, for the retailers, and for the tens of millions of families who organized their weekends around it. Then the story turns. Because through the 1970s and into the 1980s, the American mall did not just grow, it metastasized. Developers realized that malls were profit machines.
The formula was simple: buy a large, cheap plot of land on the suburban fringe, build the mall, watch the surrounding area explode with new housing, restaurants, and commercial development. Property values would skyrocket. Anchor tenants would sign long leases. Smaller retailers would pay premium rents for the foot traffic the anchors generated.
Tax revenue would pour into local governments. Everyone was getting rich, so they kept building and building and building. By 1986, the United States had roughly 25,000 retail malls and shopping centers on its landscape. Americans spent an average of 12 hours per month inside these places.
The country had accumulated nearly 24 square feet of retail space for every single man, woman, and child in the nation. For comparison, the United Kingdom had about five, Germany had two, Japan had less than two. America had built 10 to 20 times more retail space per person than any other developed nation on Earth, and nobody stopped to ask whether that made any sense. Because while it looked like infinite growth, what was actually happening was something much more destructive.
Each new mall required a large, cheap plot of land, so developers built them further and further out on the suburban fringe. New housing and commercial development quickly surrounded the new mall. Families drifted away from the older neighborhoods, and as soon as an even larger, flashier mall was built even further out on even cheaper land, the cycle repeated. The residents moved to the next ring.
The original mall lost its customer base. Property values fell. Retailers left. The old mall deteriorated.
This was the suburban sprawl death spiral, baked into the model from the very beginning. Every new mall built was essentially a ticking clock for the one that came before it. The industry was cannibalizing itself, one suburb at a time. Through the 1980s and into the 1990s, none of this mattered because the money was still flowing and the culture was still humming.
Some of the most iconic pop culture moments of the era were set in malls. The movie Fast Times at Ridgemont High in 1982 was essentially a love letter to mall culture. Tiffany performed her hit single on a mall tour in 1987, drawing massive crowds to shopping centers across the country. The opening of the Mall of America in Bloomington, Minnesota, in 1992, a 5.
6 million square foot behemoth featuring an indoor amusement park, an aquarium, and over 500 stores, was the cathedral of American consumerism, and people made pilgrimages to it from across the country. The mall was not just surviving, it was thriving. But beneath the surface, the foundation was already cracking. The entire economic model of the American mall rested on one critical pillar: the anchor tenant.
These were the massive department stores, names like Sears, J. C. Penney, Macy’s, Nordstrom, Lord & Taylor, and Dillard’s, that occupied the huge multi-story buildings at the entrances of every mall. The anchors were the gravitational center of the whole operation.
They drew the foot traffic, they paid for the advertising, they generated the customer flow that kept the smaller specialty shops alive. In return, the anchors typically paid far lower rents than the smaller tenants, sometimes almost nothing at all, because the value they brought was in the crowds, not the lease payments. This arrangement worked perfectly as long as the anchors stayed healthy. But starting in the late 1990s and accelerating through the 2000s, the American department store began to die.
Consider the most dramatic fall, Sears. At its peak, Sears was not just a department store, it was one of the 10 most valuable companies in America. It was the Amazon of its era, a retailer so dominant that it literally published a catalog through which Americans could buy everything from socks to prefabricated houses. At its height, Sears operated roughly 3,500 stores.
By 2025, fewer than 10 remained. The company filed for bankruptcy in October of 2018, and what was left was little more than a ghost, a brand name attached to empty parking lots and darkened storefronts. JCPenney followed a similar trajectory, closing around 200 stores during its 2020 bankruptcy and continuing to cut locations in the years that followed. Macy’s announced its so-called bold new chapter strategy in February of 2024, planning to shutter 150 stores by 2026.
Nordstrom scaled back. Lord & Taylor closed entirely. Bon-Ton, a department store chain with 250 locations, liquidated in 2018. The numbers are staggering.
In a span of just 24 months during 2017 and 2018, more than 600 anchor store locations went dark across America, and the impact on the malls that depended on them was catastrophic. When an anchor tenant closes, foot traffic to that mall drops by 20 to 25% almost immediately. But the damage does not stop there. Most smaller tenants in a mall have something called a co-tenancy clause written into their lease.
This clause essentially says that if a major anchor leaves, the smaller tenants can either renegotiate their rent downward or break their lease entirely. So when Sears closes, it is not just Sears that is gone. The shoe store next to it starts paying less rent. The clothing boutique on the second floor triggers its exit clause.
The pretzel stand in the food court loses half its customers. The whole ecosystem starts collapsing inward, like a building losing its load-bearing walls. That is exactly what happened across hundreds of American malls throughout the 2010s. And then there is the single biggest external force that accelerated the mall’s demise: the rise of e-commerce.
In 1994, a man named Jeff Bezos founded a small online bookstore in his garage in Bellevue, Washington. He called it Amazon. Within a decade, Amazon had expanded far beyond books into electronics, clothing, household goods, and eventually almost everything you could imagine. By 2017, a Business Insider analysis concluded that Amazon alone was generating more than 50% of all retail sales growth in the United States.
It was a single company producing more growth than every mall, department store, and Main Street shop in the country combined. Between 2015 and 2025, in-store shopping in New York City declined by 77% while online orders surged by over 100%. Chicago and San Francisco both saw 70% drops in physical retail visits over the same period. Major brands shifted their sales online.
Nike reported that 26% of its revenue came through digital channels. Gap pushed 35% of its sales online. Sephora moved a quarter of its business from physical mall locations to its website. E-commerce did not just compete with physical stores, it undermined the very reason people went to malls in the first place.
The mall’s original value proposition was convenience. You could find everything under one roof. You did not have to drive from store to store in the rain. But when you could find everything on a screen in your pajamas, delivered to your door the next day, the convenience argument evaporated overnight.
Then came the event nobody saw coming. In March of 2020, the world shut down. The COVID-19 pandemic forced malls across America to close their doors for weeks, in some cases months. Foot traffic did not just decline, it vanished.
A record 12,000 stores closed in 2020 alone. Major retailers that had been hanging on by a thread finally snapped. JCPenney filed for bankruptcy. J.
Crew filed. Neiman Marcus filed. Brooks Brothers, a company that had been dressing American professionals for over 200 years, filed for bankruptcy. What made the pandemic different from every other challenge the mall industry had faced is that it permanently changed habits.
The shoppers who discovered during lockdown that they could get everything delivered to their homes, many of them never came back. Even by 2024, mall foot traffic remained 35% below pre-pandemic levels. But to truly understand why the American mall died, you have to zoom out even further. E-commerce and the pandemic were accelerants, but they were not the root cause.
The root cause was something that had been building for decades, something structural and almost invisible. America was simply absurdly, grotesquely overbuilt in retail. That number, 24 square feet of retail space per person, is not just more than Europe, it is eight times more than Spain, nine times more than Italy, 11 times more than Germany, 22 times more than Mexico, 51 times more than China, and roughly 400 times more than India. Americans did not need 400 times more shopping space than Indians, or 11 times more than Germans.
Nobody on Earth needed that much retail, but developers kept building it because the economics of mall construction were irresistible in the short term and the consequences were someone else’s problem in the long term. This overbuilding was fueled by a peculiar feature of the American financial system. Commercial real estate in the United States is heavily incentivized by the tax code. Developers could depreciate the value of their buildings over time, reducing their tax liability.
They could leverage cheap debt. They could flip properties. Crucially, the success of a new development was not measured by whether the country needed another mall. It was measured by whether someone would finance it, and for decades, someone always would.
The result was a kind of retail arms race. Every city, every suburb, every exurban outpost was competing for the next big mall. Local governments offered tax breaks and infrastructure subsidies to lure developers, hoping the new mall would generate sales tax revenue and create jobs. But when three malls were built within 20 miles of each other, all competing for the same pool of shoppers, the math simply stopped working.
The pie did not get bigger, it just got sliced thinner. Not all malls are dying equally, though. If you look at the data carefully, what you see is a dramatic bifurcation, a splitting of the industry into two completely different worlds. On one end, you have what the industry calls class A malls.
These are the premium properties in wealthy, high-traffic locations, like South Coast Plaza in Costa Mesa, California, the Galleria in Houston, and Tyson’s Corner Center in Virginia. These malls have occupancy rates hovering around 95%. They have seen an average 12% increase in foot traffic since the pandemic. They have reinvented themselves as luxury destinations, places where you do not just shop, but dine, see art, attend events, and experience something you cannot replicate on a screen.
On the other end, you have class B, C, and D malls. These are the ones in smaller cities, in declining suburbs, in communities where incomes are stagnant and populations are shrinking. These are the ones with the boarded-up anchor stores, the empty corridors, the crumbling parking lots. An estimated 31% of all American malls fall into this lower tier, and these are the properties that are dying in real time.
Many of them already qualify as what the industry euphemistically calls zombie malls. Technically still open, but functionally dead, with vacancy rates that are 248% higher than the overall retail average. The gap between these two worlds is not closing, it is widening. The strong malls are getting stronger, attracting the best tenants and the wealthiest shoppers.
The weak malls are spiraling downward, losing tenants, losing traffic, losing value. The average vacant mall sells at 43% below its original acquisition price. And once a mall goes dark, it stays dark for an average of 3 years and 11 months before anything happens to it. What happens to dead malls is one of the more fascinating parts of this story, because it turns out that a dead shopping mall sitting on 50 acres of prime suburban land near a highway interchange with existing infrastructure and massive parking lots is actually a redevelopment goldmine.
Nearly half of all mall redevelopments are mixed-use projects that combine retail, residential, and commercial space. About 31% of vacant malls are reborn with new retail tenants through pop-up shops or reimagined storefronts. 9% become warehouses. 7% are converted into residential housing.
5% become delivery and distribution centers, many of them serving the very e-commerce companies that helped kill the mall in the first place. And about 4% are transformed into community colleges, medical facilities, or civic spaces. Take Landmark Mall in Alexandria, Virginia. When it closed in 2017, the 51-acre site sat empty for years.
But now it is being redeveloped into a $2 billion mixed-use community featuring 4,400 apartments, a hospital, parks, and retail space. It will have more housing than the original mall ever had shopping. Or consider the fact that Amazon itself has partnered with Simon Property Group, one of the largest mall owners in America, to convert former Sears and JCPenney spaces into Amazon fulfillment centers. The company that did more than any other to destroy the American mall is now literally moving into the buildings it killed.
And then there is the cultural dimension. When a mall dies, it is not just a commercial property that closes, it is a community institution. For millions of Americans, especially in smaller cities and rural-adjacent suburbs, the mall was the only public indoor space within miles. It was where elderly people walked for exercise on winter mornings.
It was where teenagers had their first unsupervised social experiences. It was where families went when they needed to feel like they were somewhere doing something, even if they were not buying anything. In the mid-1990s, Americans made an estimated 5. 6 billion trips to shopping malls every year.
That number has since fallen below 3 billion. What replaced those trips is not another physical gathering place. It is a screen. It is scrolling through Instagram.
It is adding items to an Amazon cart at midnight. The mall did not just lose to e-commerce, it lost to isolation, and the communities that depended on it lost something that no algorithm or delivery drone can replace. Victor Gruen, the man who started it all, lived long enough to see what his creation became, and he hated it. By the 1970s, Gruen had publicly disowned the suburban shopping mall.
He called it a bastardization of his original vision, a distortion of everything he had intended. He dreamed of a community center that happened to include shops. What America built was a consumption machine that happened to have air conditioning. Gruen moved back to Vienna in 1968, and he spent the last decade of his life advocating for the kinds of walkable, mixed-use urban neighborhoods that were the exact opposite of what American malls had become.
He died in 1980, just as the mall was entering its most excessive, most bloated, most culturally dominant phase. He never saw the collapse, but the collapse was inevitable. The American mall was built on a series of assumptions that all turned out to be wrong. That suburbs would keep growing forever.
That department stores would always anchor the model. That Americans would always prefer driving to a climate-controlled box over every other form of shopping and socializing. That you could keep building more retail space indefinitely without saturating the market. Every single one of those assumptions shattered.
What we are left with is something that looks a lot like a reckoning. Not just for the mall industry, but for the entire philosophy of development that powered American suburbia for half a century. The idea that you could build your way to prosperity by paving over farmland, constructing identical structures on the cheapest available land, and assuming that growth would be permanent. That model is broken.
The dead malls are not just a retail story, they are a mirror. They reflect an entire way of thinking about growth, about community, about public space, about what it means to be a society that chose convenience over connection and scale over sustainability. Not all malls will die. The luxury ones will survive.
The ones that reinvent themselves as mixed-use hubs, as medical campuses, as residential communities with a bit of retail woven in, those will survive too. The mall of the future, if it exists at all, will not be a shopping center. It will be a community center that happens to have some stores, which, ironically, is exactly what Victor Gruen wanted in the first place. So the next time you drive past a dead mall, one of those hulking, empty structures surrounded by cracked parking lots and overgrown weeds, take a moment to think about what it represents.
It is not just a failed business. It is a monument to an era when America believed that bigger was always better, that growth could go on forever, and that a building full of stores could serve as the heart of a community. That era is over, and what comes next is still being written.
